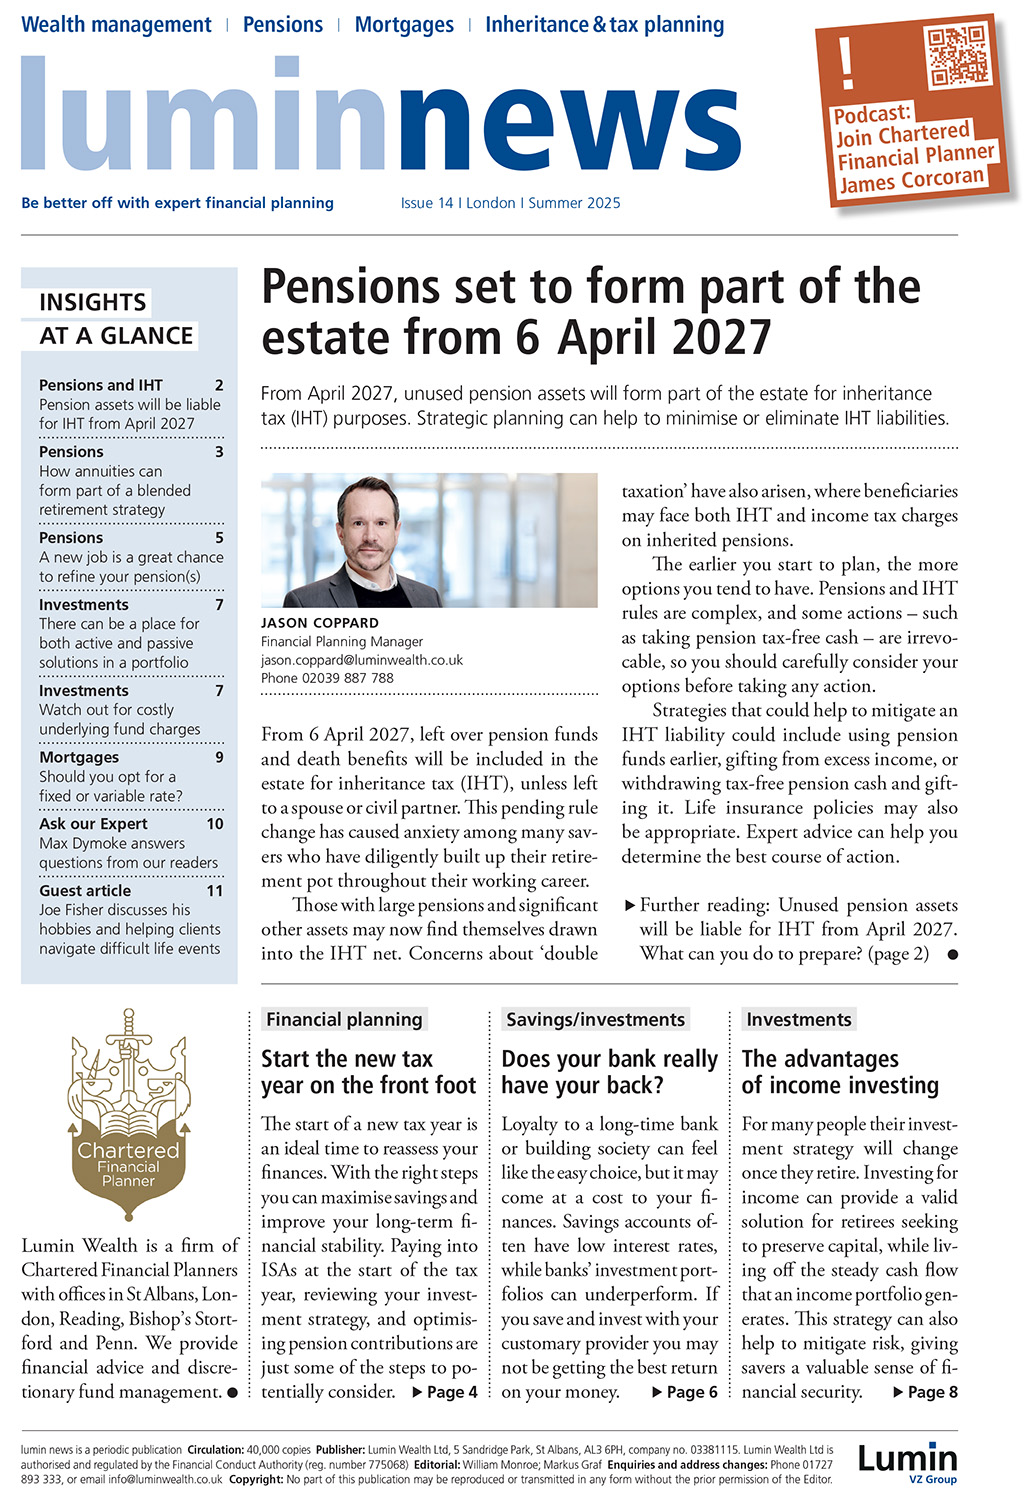

Back in 2024, the ex-Chancellor of the Exchequer Rachel Reeves announced that from April 2027, unused pension funds will fall within the scope of Inheritance Tax, unless passed to a spouse or civil partner.
If offsetting Inheritance Tax (IHT) is a key concern, the months ahead are a good opportunity to understand how these changes could affect your estate planning strategy. But more importantly, what you should do next.
What’s changing?
Up until now, pensions – including Self-Invested Personal Pensions (SIPP) and any other Defined Contribution schemes – have generally been considered outside the scope of Inheritance Tax. However, from April 2027, that will all change, unless the pension funds are left to a spouse or a civil partner.
Those estates which currently have limited to no Inheritance Tax exposure could now potentially be liable to a large Inheritance Tax bill of 40% upon death.
Note: A child inheriting pension funds after a parent dies post-75 could face 40% IHT and 45% Income Tax – an effective tax rate of up to 67%. However, relief is available against double taxation, reducing the taxable income attributable to Inheritance Tax paid. This simply reinforces the need for holistic financial planning.
Who will this impact?
Those with substantial pension pots will now have to be mindful of the large tax liability they face upon death after April 2027, where the total value of the estate exceeds the available nil-rate bands and applicable reliefs.
Tip: Married couples/civil partners could benefit from a total IHT-exempt amount of up to £1,000,000, if they make full use of the nil-rate band threshold (£325,000 each), and the residence nil-rate band of £175,000 per person (which applies where the main residence is left to direct descendants).
With pensions being added to the mix of taxable assets – which already include ISAs, the family home (beyond available allowances), rental properties, and cash savings – the Inheritance Tax liability for children could go from small to significant. There is also a risk that some savers will exceed the £2,000,000 threshold, at which point the residence nil-rate band of £175,000 starts to taper away (the allowance is reduced by £1 for every £2 above the £2,000,000 ceiling).
Download our comprehensive guide on Pensions & Inheritance Tax here.
Financial planning considerations
There exist a series of financial planning measures a Financial Consultant can help you work through.
1) Consider pensions first
From April 2027, it may make more sense to draw on pensions earlier, rather than later, in the retirement years. This shift in strategy will help reduce the amount of pension assets being exposed to Inheritance Tax later down the line.
2) Use tax-free cash
The 25% tax-free lump sum is a valuable benefit. However, from 2027, if left within the pension, it may form part of the taxable estate. If gifting to family is relevant, an expert can help you re-view the implications and cashflow needs.
3) Lifetime gifting
Gifts from excess income (immediately IHT-free) and potentially exempt transfers (PETs) should be reviewed now, while you are healthy and as the 7-year clock will start ticking.
4) Consider insurance
A whole-of-life insurance policy held in trust can provide funds to settle the IHT bill. This involves drawing on pension assets early and turning them into guaranteed income upon death. This prevents beneficiaries from needing to sell large assets such as property.
Acting now could give you more options to reduce the impact of the April 2027 changes. Call 03300 564 446 or get in touch via our contact form to book a free, no-obligation meeting with a Financial Consultant.
This article is for general information purposes only and does not constitute financial advice or a personal recommendation. Past performance is not a reliable indicator of future results. Investments can rise or fall in value, and you may receive less than you originally invested. Tax treatment depends on individual circumstances and may change in the future.