After much anticipation, the recently elected Prime Minister, Andy Burnham, and Chancellor of the Exchequer, John Healey, will be setting out their economic outlook in the 2026 Autumn Budget. So, what’s being discussed and what does it mean for your financial planning?
On Wednesday 28th October, Chancellor John Healey will take centre stage to deliver the keenly awaited Autumn Budget. The announcements could mark a turning point in economic policy. For anyone with savings, investments, a pension, or a property, Budget Day is always worth paying attention to – this year, perhaps more than most.
Nothing explicit has been revealed by the newly appointed chancellor or cabinet. But what we can glean from Healey so far is that it will be “built on fiscal discipline” while also giving “businesses and families some of the stability they need to plan for the future”. Given the recent record-highs of UK borrowing costs since the 2008 financial crisis, however, this could be an ambitious balance to strike and may bring tax policy firmly into the spotlight, rather than relying on spending cuts to balance the books.
Below, we summarise what’s already confirmed, what’s being widely discussed, but most importantly, what this could mean for your own financial planning.
What’s already confirmed from previous Budgets?
Following the last few Budgets, there are already a handful of measures locked in place:
1) VAT removed from electricity bills
From 1 October 2026, VAT will no longer apply to domestic electricity bills – one of the Prime Minister’s first acts in office, expected to save the average household in the region of £45 a year.
2) Pensions and Inheritance Tax (IHT)
Marking one of the biggest financial planning consequences in years, ex-Chancellor Rachel Reeves announced back in 2024, pensions will fall into the Inheritance Tax (IHT) net from 6th April 2027 as “notional pension property”. This means that any unused pension funds will be included in the calculation of IHT and may possibly impact other allowances, such as, the Residence Nil Rate Band (RNRB). Until now, pensions have been considered an effective way of passing down wealth, but from April 2027, that will no longer be the case. Many people will now need to revisit how they plan to draw down retirement income and what they leave behind.
3) ISA reform
Also from 6th April 2027 and coming off the back of the Autumn 2025 Budget, the Cash ISA allowance is due to fall from £20,000 to £12,000 for savers under 65 (the overall £20,000 ISA allowance stays the same). Also from April 2027, interest earned on cash held in a non-Cash ISA, such as Stocks & Shares ISAs, will be taxed at a flat rate of 22% and investors will no longer be able to hold their entire ISA portfolio in alternative ‘cash like’ Money Market Funds. This move is intended to encourage more people to invest their money, rather than store large sums in cash.
4) A new surcharge on high-value homes (“High Value Council Tax Surcharge” HVCTS)
From April 2028, residential properties in England worth more than £2 million will face an annual surcharge, expected to range from £2,500 to £7,500 depending on value.
Note: All the changes outlined above will not be announced on 28th October. Nonetheless, the upcoming Budget marks an optimal window to see if your current financial plans align with them.
What’s expected to come out of the next Autumn Budget?
Although nothing will be confirmed until 28th October, rumours are swirling and speculation is mounting. While drastic action off the back of speculation is not warranted, you can take steps now to utilise existing tax allowances.
1) Capital gains tax (CGT)
The direction of Burnham’s economic policy appears to be towards higher taxation of wealth and assets, rather than higher taxes on earned income, signally a potential change in capital gains tax (CGT). The main rate was last increased in October 2024 when most assets moved from 10%/20% to the current 18%/24%, with many commentators expecting this to further increase.
2) Inheritance Tax (IHT)
Although not formally proposed, Burnham has spoken about reforming Inheritance Tax (IHT), including the idea of replacing the current system with a broader estate levy, and has been reported as willing to revisit recent changes to agricultural (APR) and business property relief (BPR).
3) Land and property taxation
Despite no concrete or immediate plans to abolish stamp duty or council tax by the Prime Minister himself, a land value tax has been floated as a longer-term idea.
4) State Pension age
Under current rules, the State Pension age starts increasing from 67 to 68 is set to take effect from 2044. However, the OBR has suggested it could happen as early as 2037 to 2039.
5) Income tax, National Insurance and VAT
The government has repeated its manifesto commitment not to raise the headline rates of these three taxes for the rest of this Parliament. However, as with any Budget speculation, nothing is guaranteed until it’s announced.
What Autumn Budget speculation means for your financial planning
Budget speculation can be noisy, confusing and make you feel like you should react to every headline. But in practice, the run up to any Autumn Budget should be about creating a flexible and resilient plan that can withstand a range of outcomes and then fine-tuned as and when changes are firmly announced.
That’s particularly true for the two changes we already know are coming. The changes coming to pensions and Inheritance Tax (IHT) from April 2027, for instance, is triggering many to rethink their approach to drawing on income from ISAs and savings before touching pension funds, and to consider how to restructure their estate for beneficiaries. The ISA reforms, meanwhile, affect the proportion of cash and investments you decide to hold within your tax wrapper before April 2027 hits.
But as far as the upcoming announcements are concerned, it’s worth waiting until the announcements have been made by Chancellor Healey on 28th October before taking any drastic action unless it is your intention to make the change at some point in any case.
Join our live webinar: ‘Autumn Budget Breakdown’
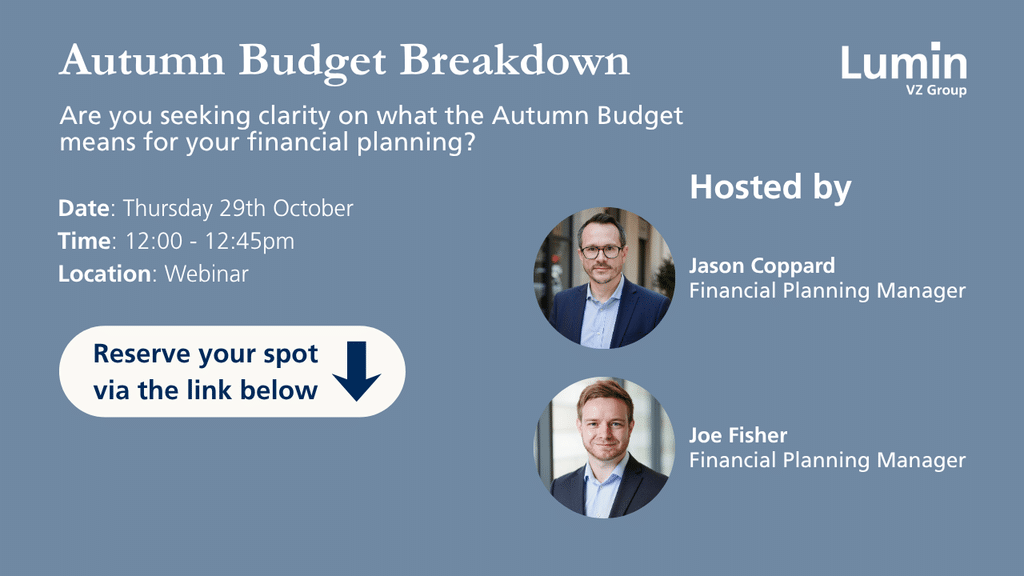
To help make sense of the announcements once they’re confirmed on 28th October, we’re hosting a free online webinar ‘Autumn Budget Breakdown’ on 29th October at 12pm – the day after the Budget. Lumin experts and Chartered Financial Planners, Jason Coppard and Joe Fisher, will unpack what was announced as they land and talk through any potential financial planning actions you should be considering off the back of the announcements. Register your place here.
This article is for general information only and does not constitute financial or tax advice. It reflects our understanding of proposals and speculation as at the date of writing; details may change when the Budget is delivered on 28th October, and some points discussed are unconfirmed. You should not make financial decisions based on this article alone. Speak to a suitably qualified adviser about your own personal circumstances. Lumin Wealth Limited is authorised and regulated by the Financial Conduct Authority (registration number 775068). The FCA does not regulate tax and estate planning.